Key figures
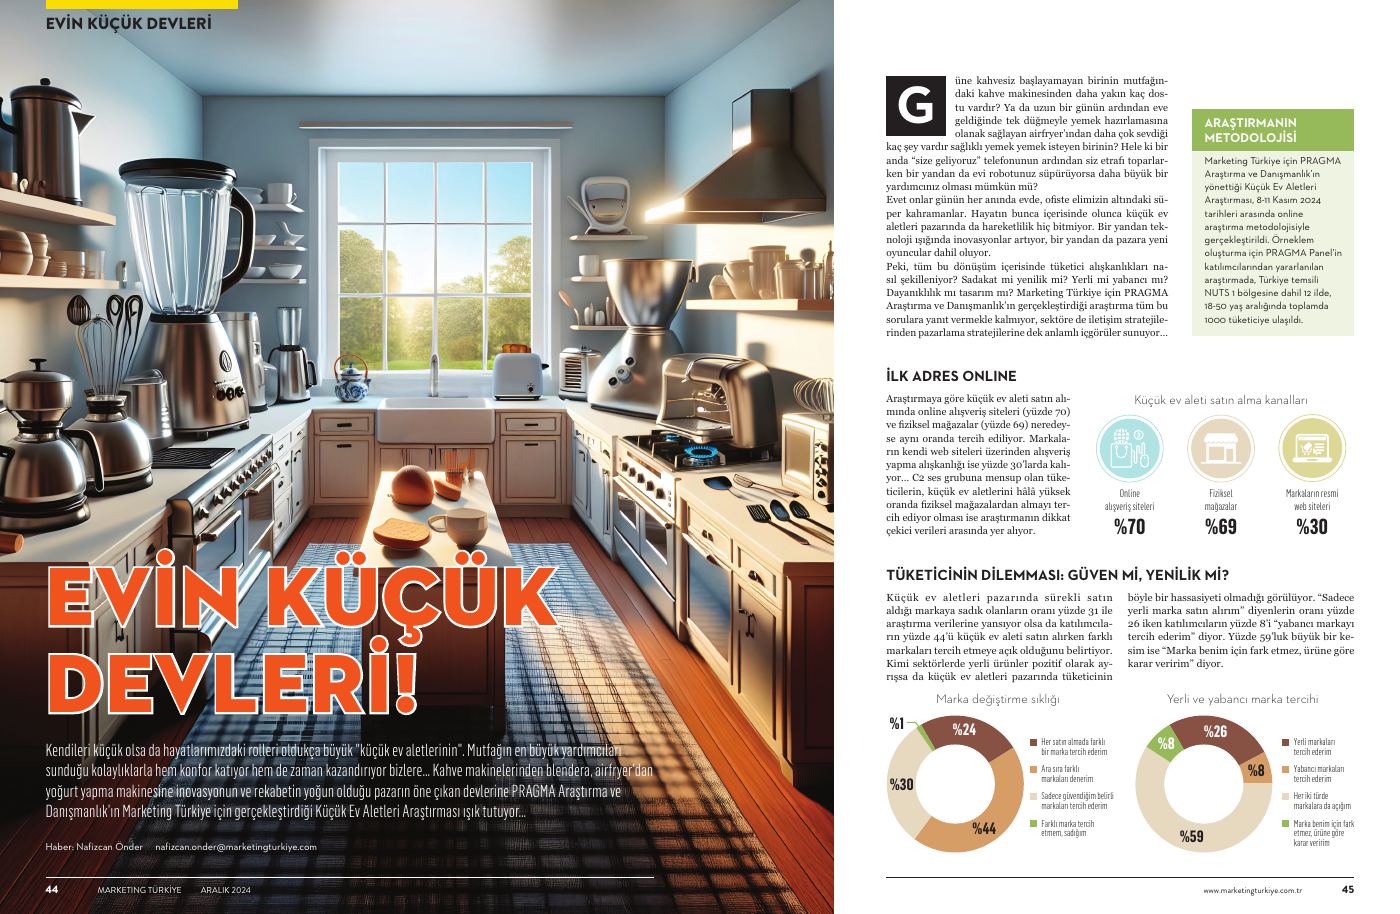
- 63%Use small appliances every day
- 79%Open to a new brand for new-generation products
- 69%New-generation product used: robot vacuum
- 1,000Participants (12 provinces, aged 18–50)
Key findings
- Online stores (70%) and physical stores (69%) are almost equal; brands’ own websites are at 30%. The C2 group still prefers stores.
- 31% always buy the same brand and 44% are open to others; for 59%, local versus foreign does not matter.
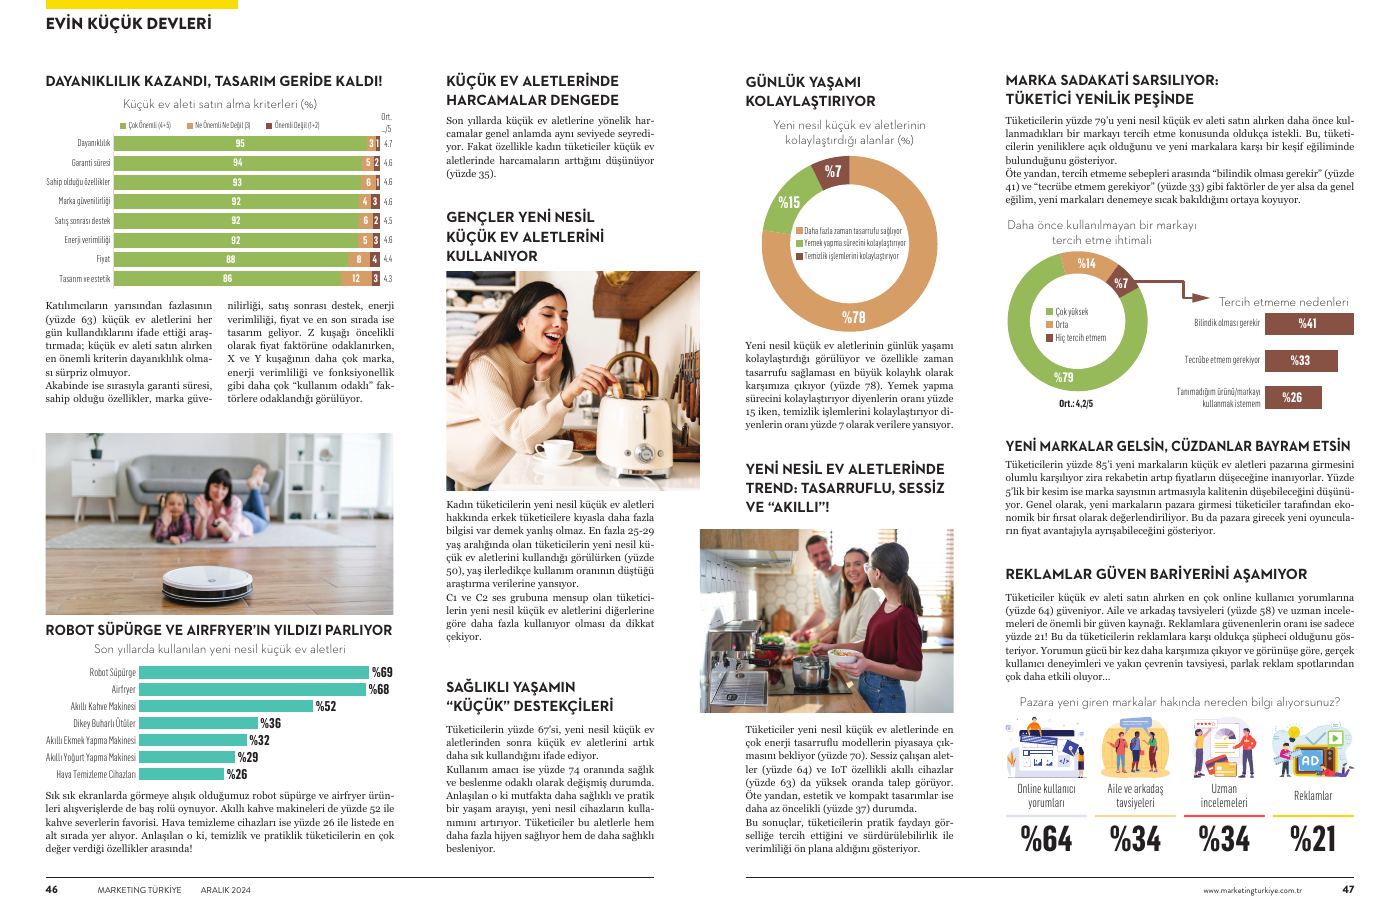
- Durability is the top criterion (95%), followed by warranty, features, brand reliability and after-sales support; design comes last.
- Gen Z focuses on price; Gen X and Y on usage factors such as brand, energy efficiency and functionality.
- Robot vacuums (69%) and air fryers (68%) are the stars; saving time is the biggest benefit (78%).
- 85% welcome new brands entering the market for more competition and lower prices.
- Online user reviews (64%) and recommendations from people they know (58%) are trusted most; only 21% trust advertising.
About the research
- Method
- Online survey, PRAGMA Panel
- Date
- 8–11 November 2024
- Sample
- 1,000 consumers aged 18–50 in 12 NUTS-1 provinces
- Partner
- Marketing Türkiye
Download the full report (PDF, in Turkish)