Key figures
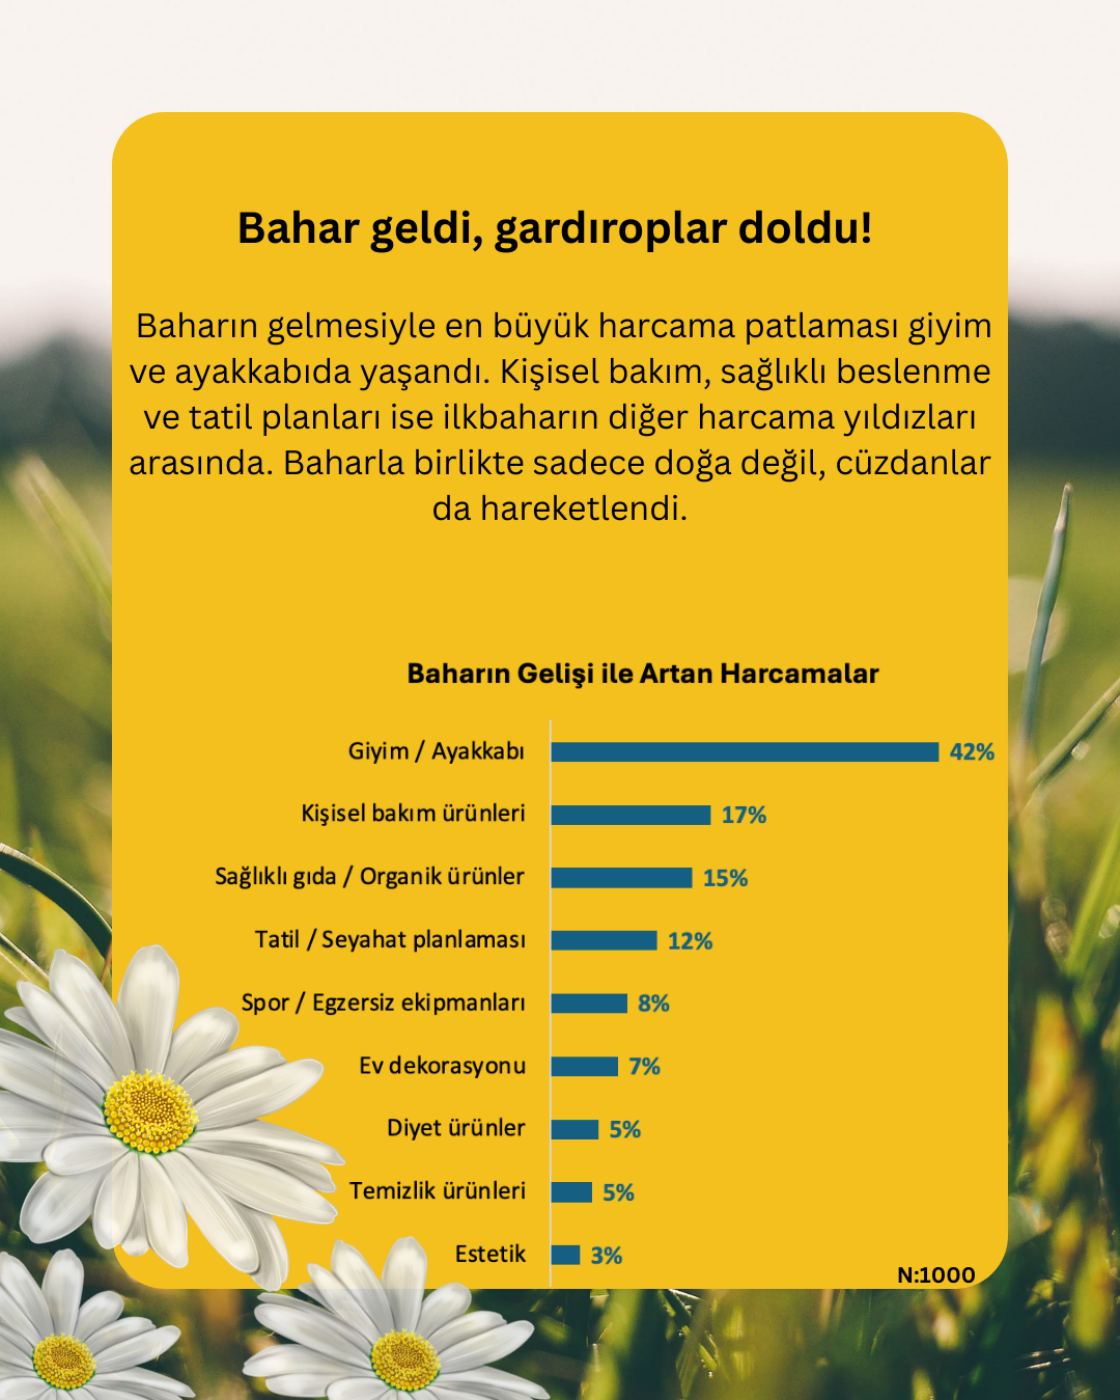
- 42%Category with the biggest rise: clothing and footwear
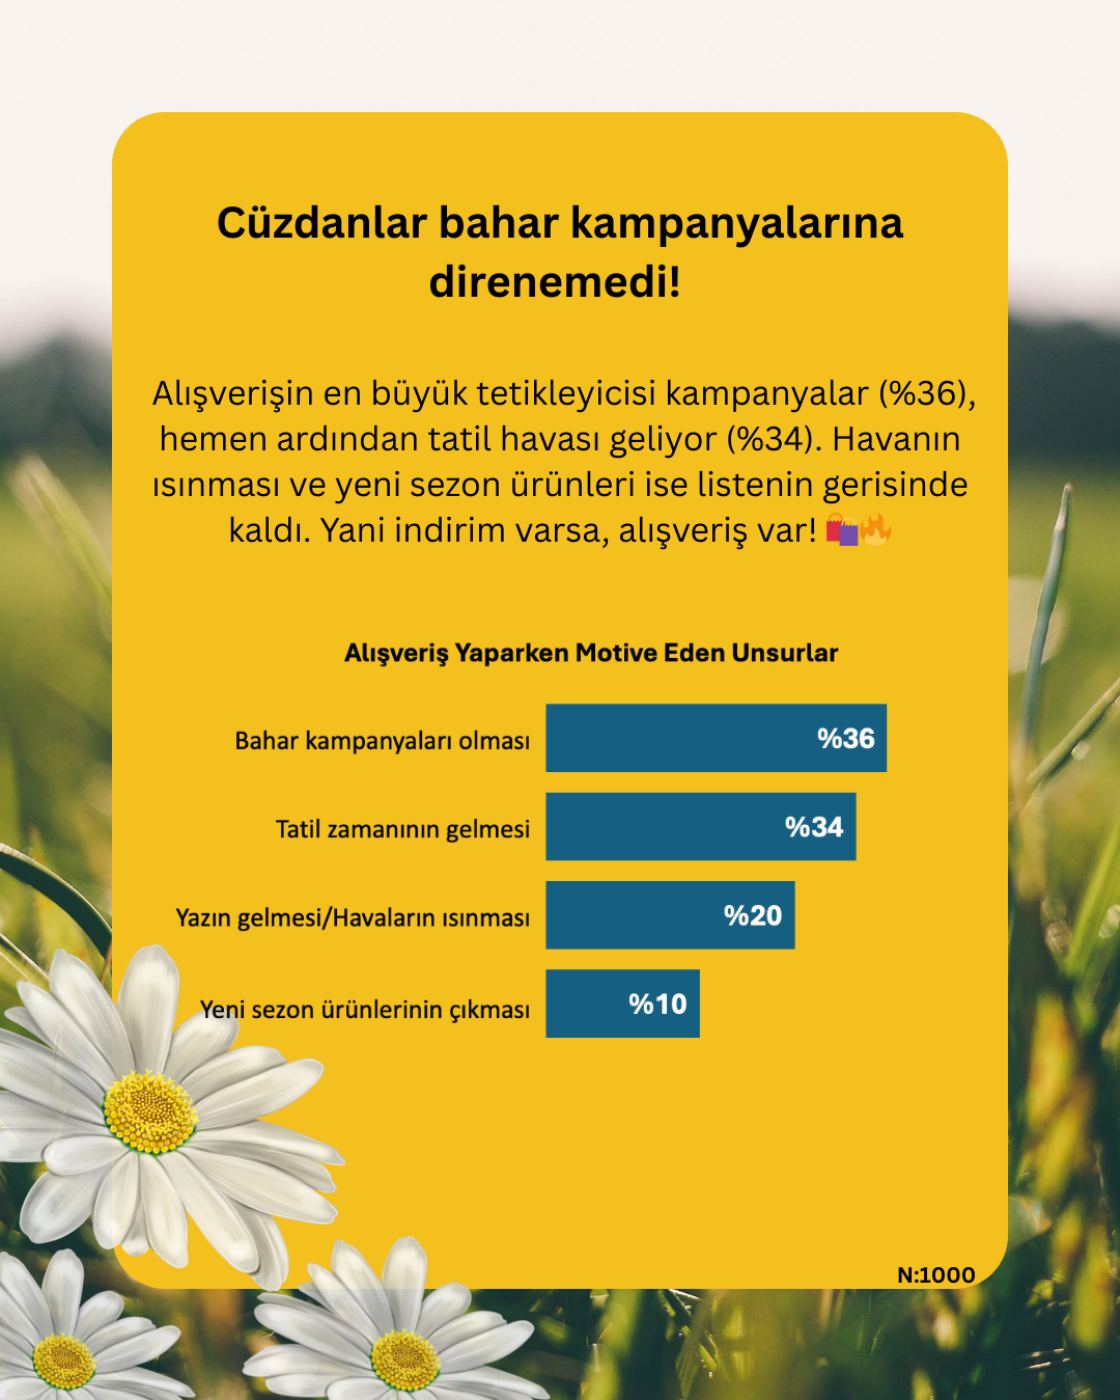
- 36%Top shopping trigger: spring campaigns
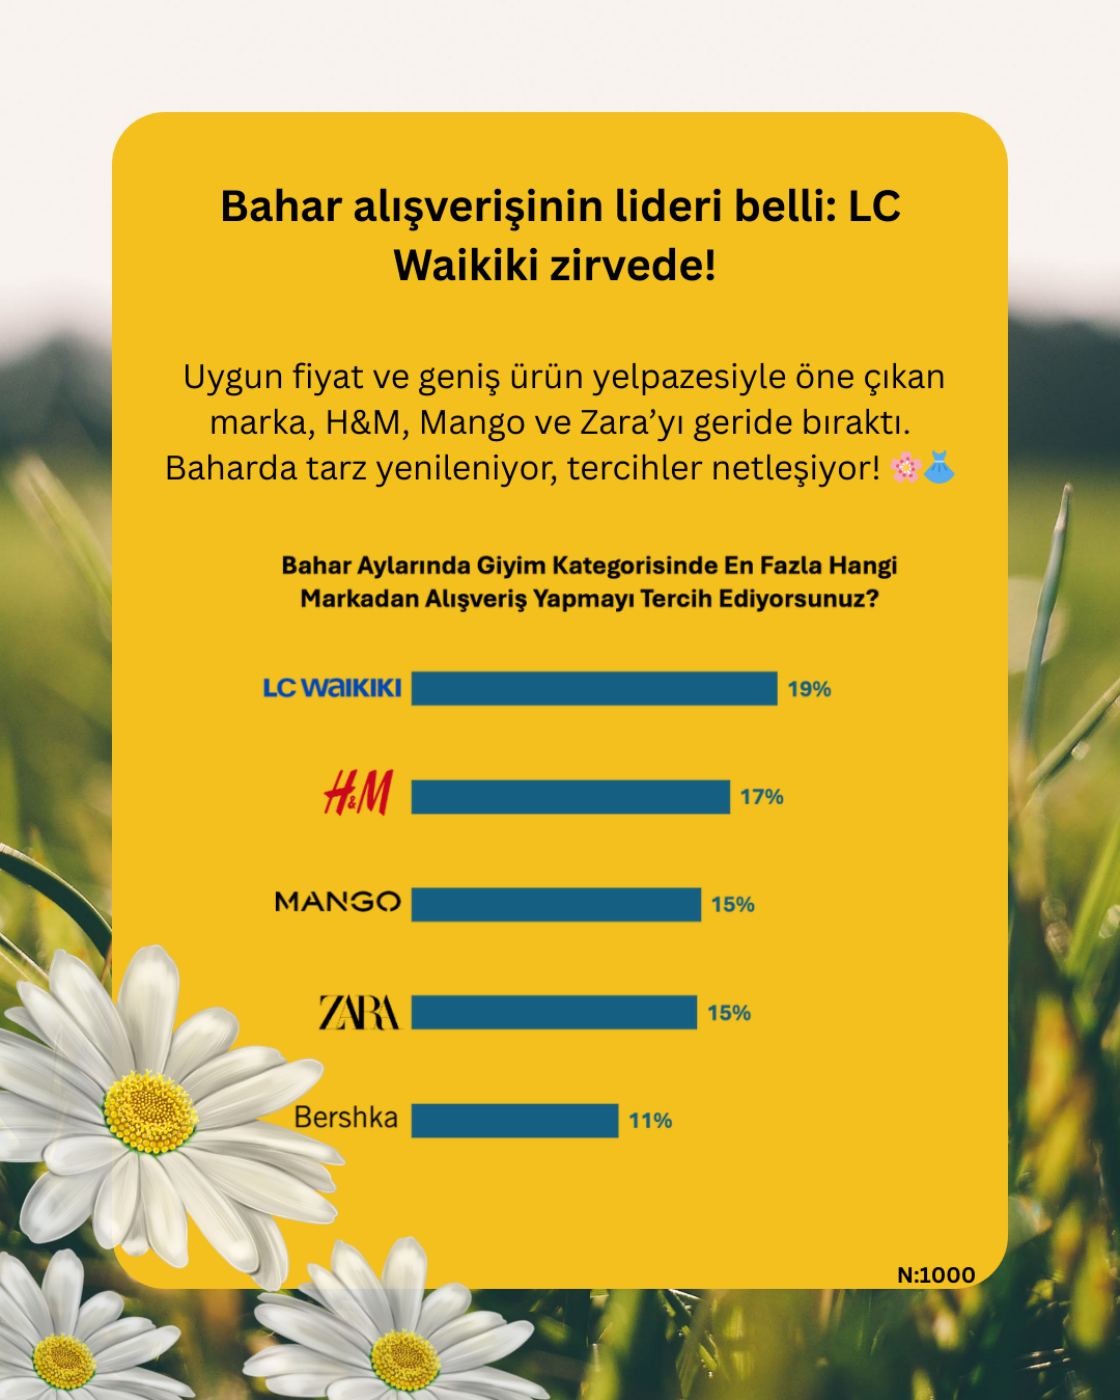
- 19%Spring clothing leader: LC Waikiki
- 1,000Participants
Key findings
- Clothing and footwear (42%) are followed by personal care (17%), healthy/organic food (15%) and holiday planning (12%).
- Campaigns (36%) and the holiday season (34%) trigger shopping most; warmer weather (20%) and new-season products (10%) lag behind.
- LC Waikiki leads spring clothing (19%), followed by H&M (17%), Mango and Zara (15% each) and Bershka (11%).
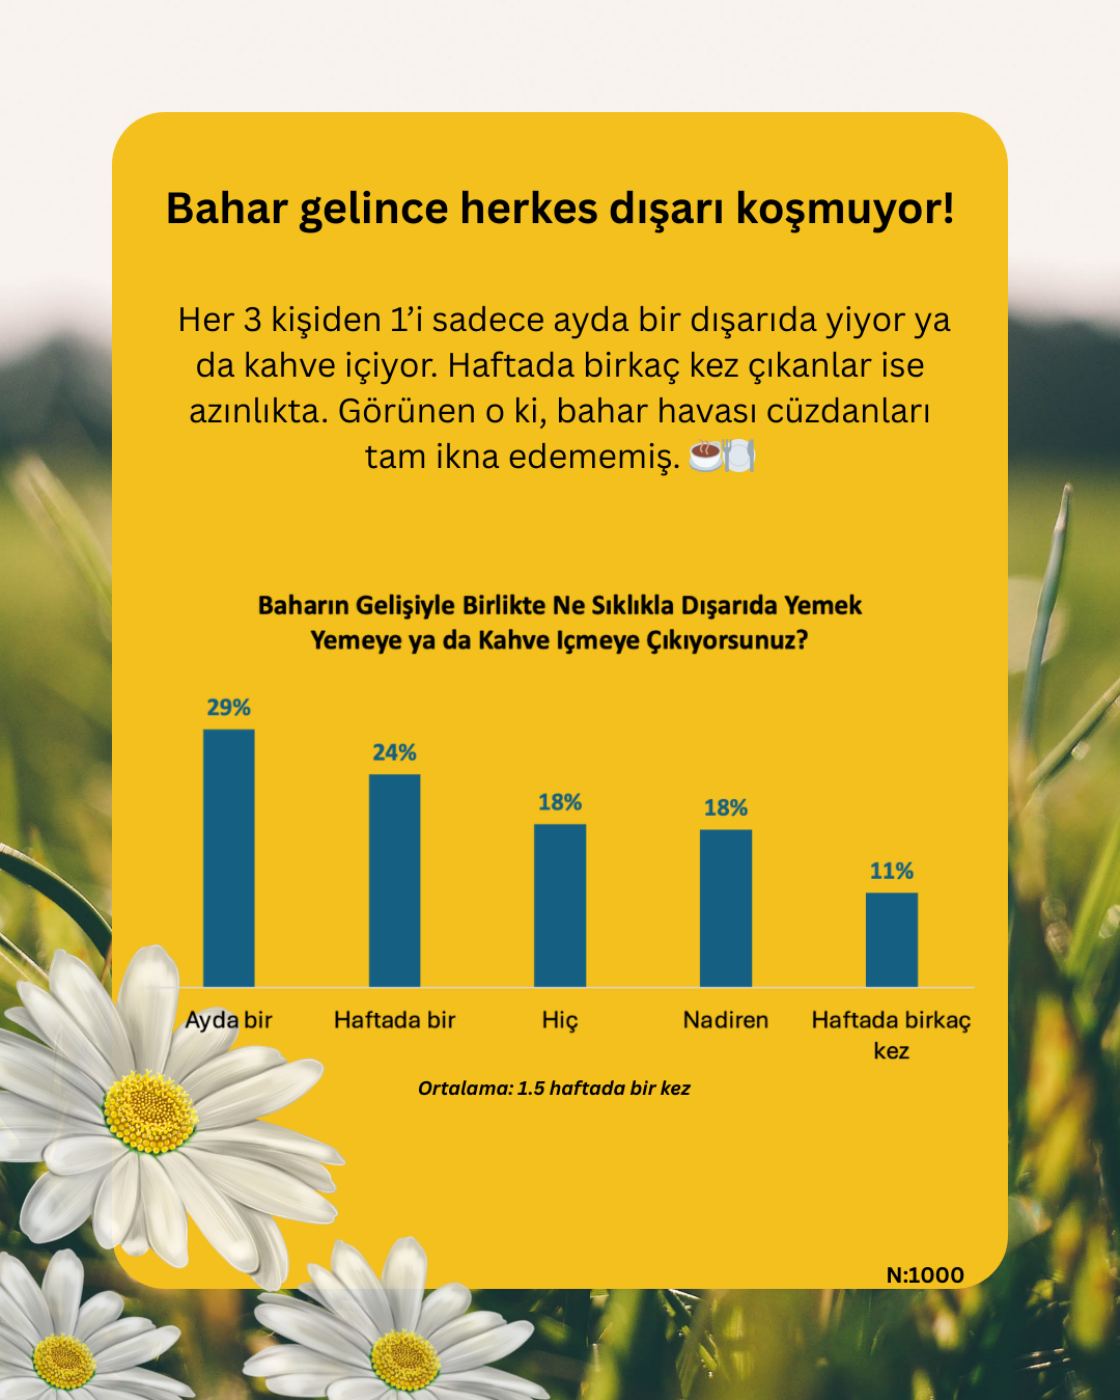
- Spring does not send everyone out: one in three eats or drinks out only once a month; 11% go out several times a week. The average is once every 1.5 weeks.
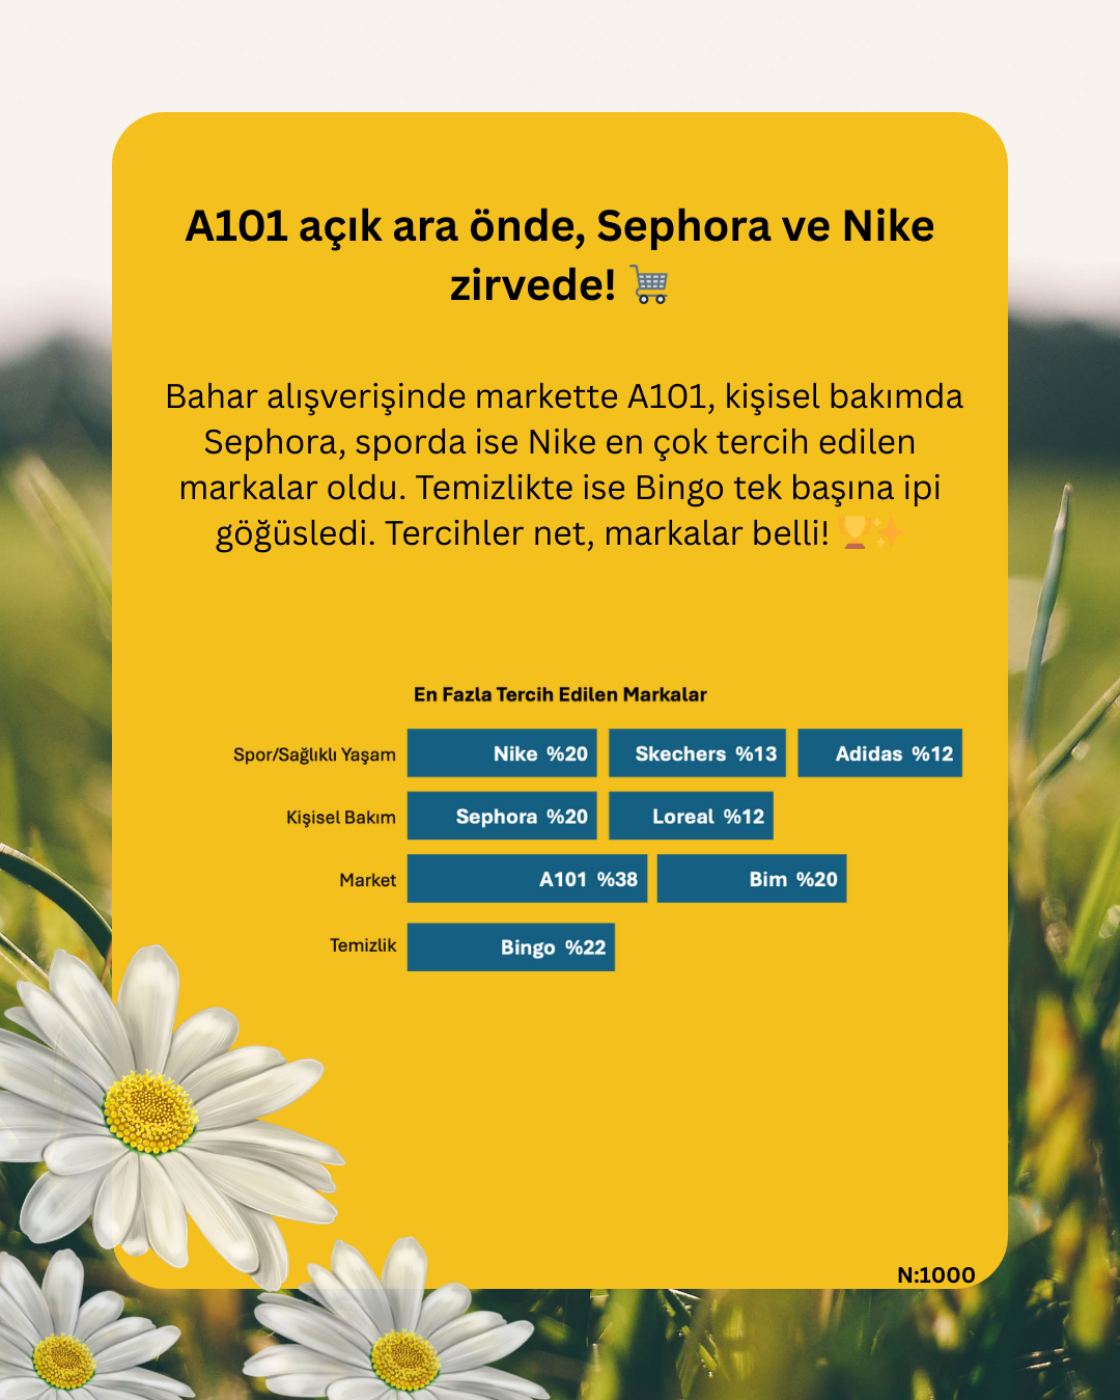
- A101 leads grocery (38%) ahead of BİM (20%); Sephora leads personal care and Nike sport (20% each), and Bingo cleaning (22%).
About the research
- Method
- Online survey, PRAGMA Panel
- Date
- Spring 2025
- Sample
- 1,000 participants
Download the full report (PDF, in Turkish)